
Strategic location
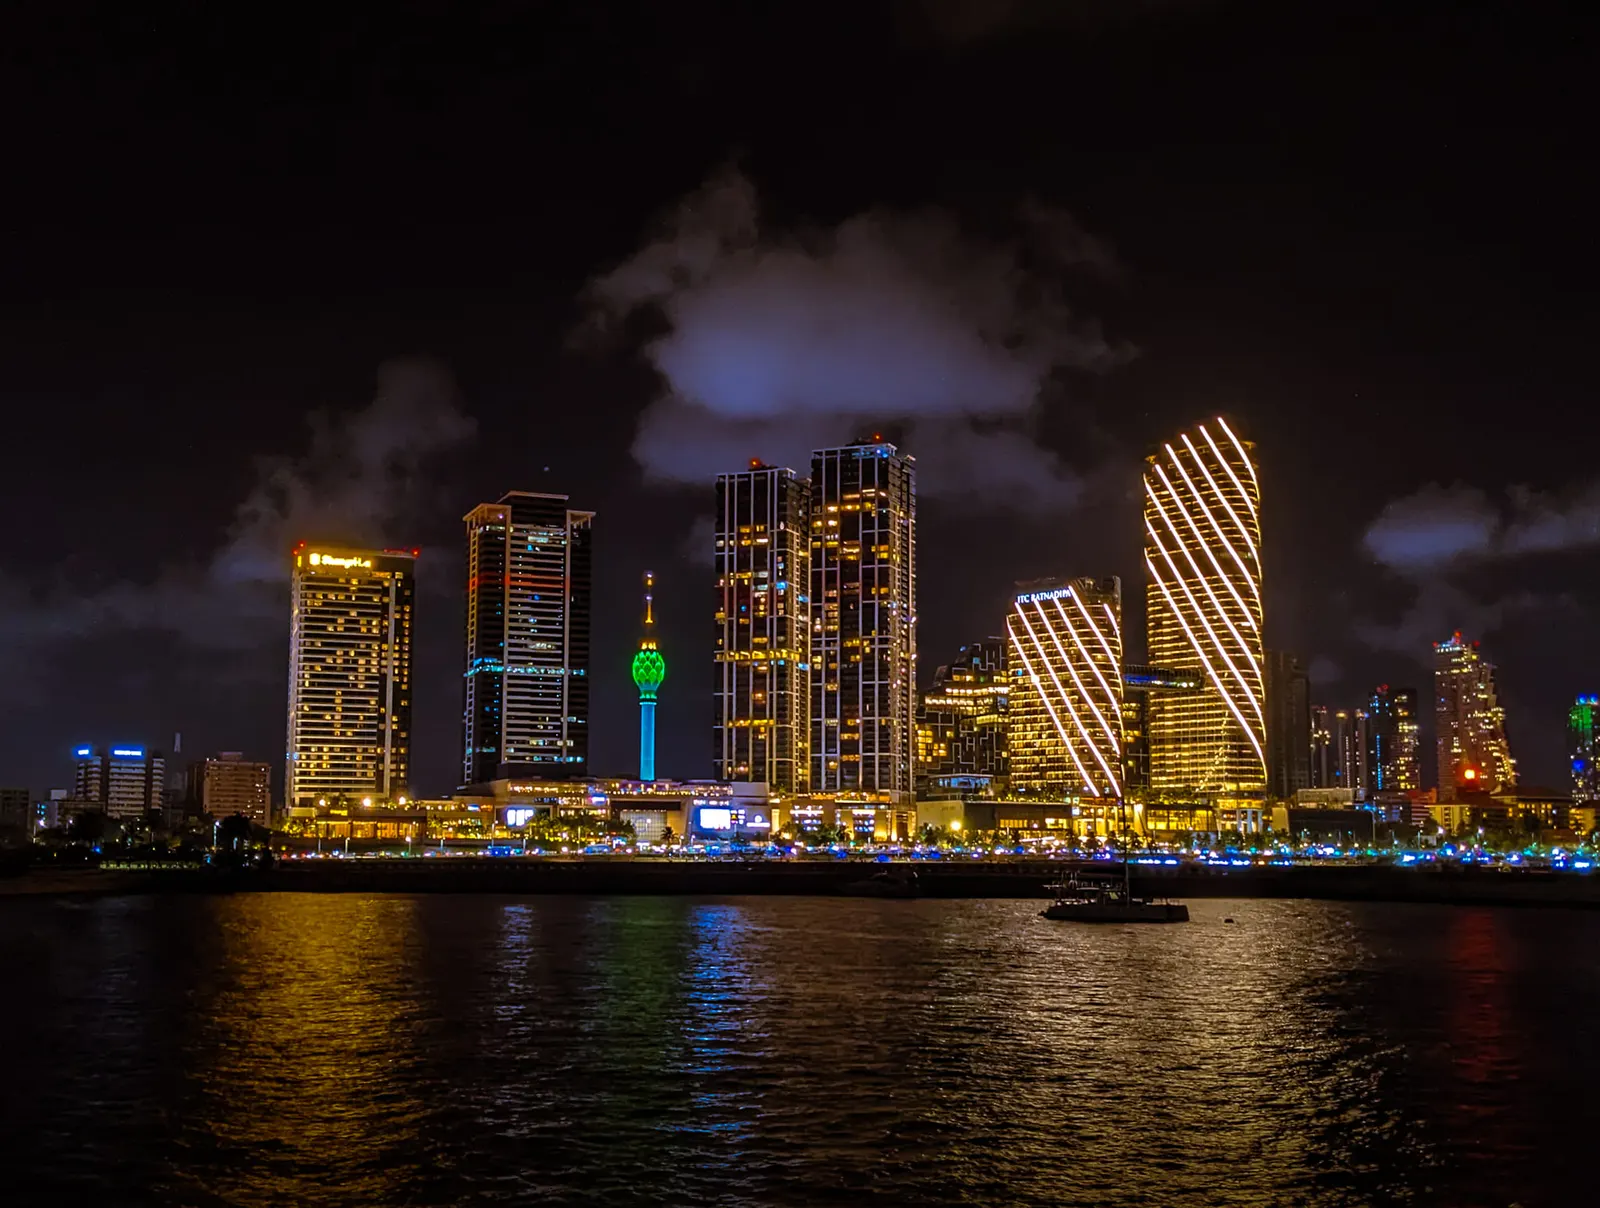
The BOI describes Sri Lanka as sitting at the crossroads of major maritime routes linking South Asia, the Far East, Europe and the Americas, and as a gateway to a market of 1.9 billion people in South Asia.
Offices in Colombo, Sri Lanka and Israel
Investment Guide
The Board of Investment of Sri Lanka (BOI) is the country’s single-window agency for attracting, approving and facilitating investment. This guide restates, in our own words, investor-relevant facts as published by the BOI. Figures and fees can change; we note the published source date where we have it.
As published by the Board of Investment of Sri Lanka. Incentive figures are taken from the BOI Investment Incentives summary dated 9 September 2026, unless another date is given. Please confirm current rules before committing capital.
At a glance
As published by the Board of Investment.
Sri Lanka
The BOI describes Sri Lanka as sitting at the crossroads of major maritime routes linking South Asia, the Far East, Europe and the Americas, and as a gateway to a market of 1.9 billion people in South Asia.
The BOI highlights a versatile, cost-competitive workforce, recognised for precision manufacturing and adaptability, with ongoing education and vocational training aimed at ICT, hospitality and tourism, light engineering and automotive manufacturing.
National priorities cited by the BOI include upgraded seaports, modernised international airports, roads and expressways, and strengthened power and telecommunications.
Official materials also point to beaches, hills, rainforests and cities, international schools and private healthcare as part of the living environment for expatriates and their families.
Sri Lanka participates in free trade and partnership agreements with major Asian economies. The BOI’s “Why Sri Lanka” page states that double taxation avoidance agreements have been signed with 45 countries (some other BOI materials cite 46).
As published by the BOI, Sri Lanka has entered into 26 bilateral investment promotion and protection treaties (BITs).
Process
Kenglobe Lanka guides you through BOI approval — this site does not publish direct filing routes.
The BOI distinguishes projects under Section 17 of the BOI Law (new companies or expansions of existing BOI companies entering a Section 17 agreement) from Section 16 arrangements (a new company with foreign shareholding of up to 100% that is not eligible to operate under Section 17, or the issue or transfer of shares in an existing non-BOI company to foreign investors).
Company names are checked under the Companies Act No. 7 of 2007, and companies are incorporated with the Registrar of Companies. Official BOI guidance states that BOI-approved projects must obtain prior approval of the draft Articles of Association before incorporation.
Section 17 applications, as described in official guidance, cover both investment approval and site approval, and may require a company profile, financial references and a project report. Kenglobe Lanka prepares and coordinates this with you — we do not publish application portals or filing instructions here.
Once approved, investors enter into a BOI agreement. The BOI also describes aftercare including operational support, visa and expatriate work clearances, and help with expansions. Section 17 and Section 16 projects have different ongoing reporting and fee obligations, as published by the BOI.
Incentives
As at 9 September 2026, source: Board of Investment of Sri Lanka, Investment Incentives summary. Corporate income tax rates as published there.
30%
Standard corporate income tax rate
45%
Higher rate, in force since 1 April 2025, on gains and profits from betting and gaming, and from the manufacture and sale or import and sale of liquor or tobacco products
15%
Reduced rate on the export of services, including ICT, and on gains and profits derived from any foreign source in foreign currency
The September 2026 summary also grants enhanced capital allowances, on top of normal depreciation, for new investment and for expansions of existing BOI projects. For example, a new investment of more than USD 0.25 million and up to USD 3 million attracts a 100% enhanced allowance, with unrelieved losses deductible over 10 years; larger investments attract higher rates, with a further uplift in the Northern Province. Depreciable assets include computers and data-handling equipment, certain vehicles, and plant and machinery used in manufacturing.
For export-oriented projects, customs duty is published as exempt on capital goods (plant, machinery and equipment) for the life of the project and on construction items during the project implementation period, and on raw materials for the life of the project. For non-export-oriented projects, a customs-duty exemption is published on capital goods and construction items during implementation, with no published concession on raw materials. PAL and CESS exemptions on capital goods and construction items during implementation are published for investments of USD 50 million or more, and, for export-oriented projects, on raw materials for the life of the project.
On VAT, within specified zones (Katunayake, Biyagama, Koggala, Kandy Industrial Park, Wathupitiwala, Malwatta and Mirigama) an exemption is published for export-oriented capital goods and for raw materials for the life of the project; outside those zones, and in other zones, a deferment is generally described. Special raw-material exemptions are noted for garment and fabric manufacturers. A Commercial Hub regime (Regulation No. 1 of 2019) describes activities such as entrepot trading, offshore business, front-end services to clients abroad, buyer headquarters operations and logistics, with published minimum investment and turnover thresholds and location conditions (free port, bonded area, or outside them).
The SDP Act No. 14 of 2008 is described as the most comprehensive incentive package. Under Gazette No. 2474/66 of 8 February 2026, published bands start above USD 50 million, with corporate-income-tax holidays of 5–10 years depending on sector (infrastructure and services, tourism excluding casinos and betting, manufacturing, agriculture, education and technology) and minimum local jobs, plus import-tax exemptions on capital goods and construction materials during the project implementation period — not on motor vehicles for personal use. The corporate-tax exemption starts from the commencement of commercial operations; ordinary tax rules apply afterwards.
As at 9 September 2026, source: Board of Investment of Sri Lanka, Investment Incentives summary. For Strategic Development Projects: as at 8 February 2026, source: Gazette Extraordinary No. 2474/66. Confirm current rules before relying on these figures.
Thresholds
As published on the Board of Investment of Sri Lanka new-investor pages (source: BOI). Illustrative minimum investment qualifying criteria (USD). Confirm the current schedule before relying on a figure.
| Sector / activity | USD |
|---|---|
| IT and IT-enabled services (including local market) / BPO / training institutes / research & development | 150,000 |
| Agriculture and agro-processing (export or local market; raw materials to be sourced locally) | 150,000 |
| Regional operating headquarters | 250,000 |
| Manufacture of non-traditional goods for export, including deemed exports | 500,000 |
| Tourism & leisure; utilities (power, water, waste); export-oriented services; warehousing, logistics and cold storage | 500,000 |
| Advanced-technology or large-scale manufacturing of non-traditional goods for the local market; public-service projects as approved by the Board | 5,000,000 |
| Small-scale infrastructure: hospitals (USD 500,000); other approved infrastructure construction (USD 5,000,000) | 500,000 / 5,000,000 |
| Large-scale infrastructure as approved (power, highways, ports, airports, public transport, railways, water, industrial estates / SEZs and other approved projects) | 3,000,000–12,500,000 |
Zones
Source: Board of Investment of Sri Lanka new-investor pages. Upfront premiums and annual ground rents per acre as published there, plus VAT. Published lease period: 30 years. Land reservation fee: 10% of the land premium. Confirm current charges, which may be updated.
| Zone / park | Premium per acre (USD) | Ground rent per year (USD) |
|---|---|---|
| Katunayake EPZ | 150,000 | 12,500 |
| Biyagama EPZ | 100,000 | 10,000 |
| Seethawaka EPZ | 110,000 | 5,650 |
| Wathupitiwala EPZ | 50,000 | 5,650 |
| Horana EPZ | 45,100 | 5,650 |
| Wagawatta EPZ | 40,000 | 4,660 |
| Malwatta EPP | 37,500 | 5,650 |
| Mirigama EPZ | 35,200 | 5,650 |
| Koggala EPZ | 35,000 | 6,225 |
| Eravur EPZTextile manufacturing zone | 35,000 | 5,000 |
| Polgahawela EPZ | 30,000 | 5,650 |
| Mirijjawila EPZ | 20,000 | 4,660 |
| Arabokka EPZPharma manufacturing zone | 20,000 | 4,660 |
| Kandy IPIndustrial park | 15,000 | 5,650 |
| Mawathagama EPZ | 14,000 | 5,650 |
| Bingiriya EPZ | 10,000 | 4,235 |
The Board of Investment of Sri Lanka is the central facilitation and regulatory body for attracting, approving and expediting foreign direct investment and local capital. It describes itself as a single-window facilitator across feasibility, site selection, statutory approvals, aftercare and expansion. As published by the BOI, more than 1,600 companies operate under it, representing 64% of national exports and 485,000 direct cumulative jobs.
As described in official BOI guidance, Section 17 is used to set up a new company, or expand an existing BOI company, to operate under Section 17 of the BOI Law (typically the incentive agreement route). Section 16 is used for a new company with foreign shareholding of up to 100% that is not eligible to operate under Section 17, or for transferring or issuing shares in an existing non-BOI company to foreign investors.
In the Investment Incentives summary dated 9 September 2026, the standard corporate income tax rate is 30%, a higher rate of 45% (in force since 1 April 2025) applies to betting and gaming and to liquor or tobacco manufacture/import and sale, and a reduced 15% rate applies to the export of services including ICT and to gains from any foreign source in foreign currency.
The Strategic Development Projects Act No. 14 of 2008 is described as Sri Lanka’s most comprehensive incentive package for large, high-impact investments. Eligibility and concessions are prescribed by regulation (Gazette No. 2474/66 of 8 February 2026). Published bands start above USD 50 million of investment, with corporate-income-tax holidays of 5–10 years depending on sector and size, plus import-tax exemptions on capital goods and construction materials during the project implementation period (not including motor vehicles for personal use). Exemptions start from the commencement of commercial operations.
Official BOI guidance states that foreign investment of up to 100% is approved in activities other than certain reserved, regulated or partly restricted lists. Activities reserved for Sri Lankan citizens include pawn brokering, coastal fishing, and retail trade with capital of less than USD 5 million. Other activities (for example air transportation, coastal shipping, arms and explosives, and large-scale mechanised gem mining) require approval from other statutory agencies. In a further list — including primary processing of tea, rubber and coconut, education, freight forwarding and travel agencies — foreign investment up to 40% is approved by the BOI, and higher holdings up to 100% are considered case by case. These lists are as published in official guidance and should be confirmed as current.
On the BOI new-investor pages, zone land is listed with a non-refundable upfront premium per acre and an annual ground rent per acre (plus VAT). The published lease period is 30 years, and a land reservation fee of 10% of the land premium is listed. Examples include Katunayake EPZ (USD 150,000 premium and USD 12,500 annual rent per acre) and Bingiriya EPZ (USD 10,000 and USD 4,235). These are published charges, not an application route, and may be updated.
Some official BOI investment materials state that 100% repatriation of capital and profits is permitted, and that dividends to non-resident entities are exempt from income and withholding taxes. Treat this as published guidance to be confirmed for your structure and sector, including under the Foreign Exchange Act and any applicable BOI or Port City regime.
Kenglobe Lanka guides you through BOI approval. Contact us at sh@kenigs.com or on WhatsApp and we will coordinate the official process with you. We do not publish government application portals, office addresses or filing instructions on this site.
Guidance through BOI approval
Contact us by email or WhatsApp and we will coordinate the official process, from choosing the right route through to the agreement and aftercare. Initial consultation is free of charge.